Retirement changes the way you look at money. During your working years, your focus is on earning and accumulating wealth. After retirement, the priority shifts to generating regular income while making your savings last.
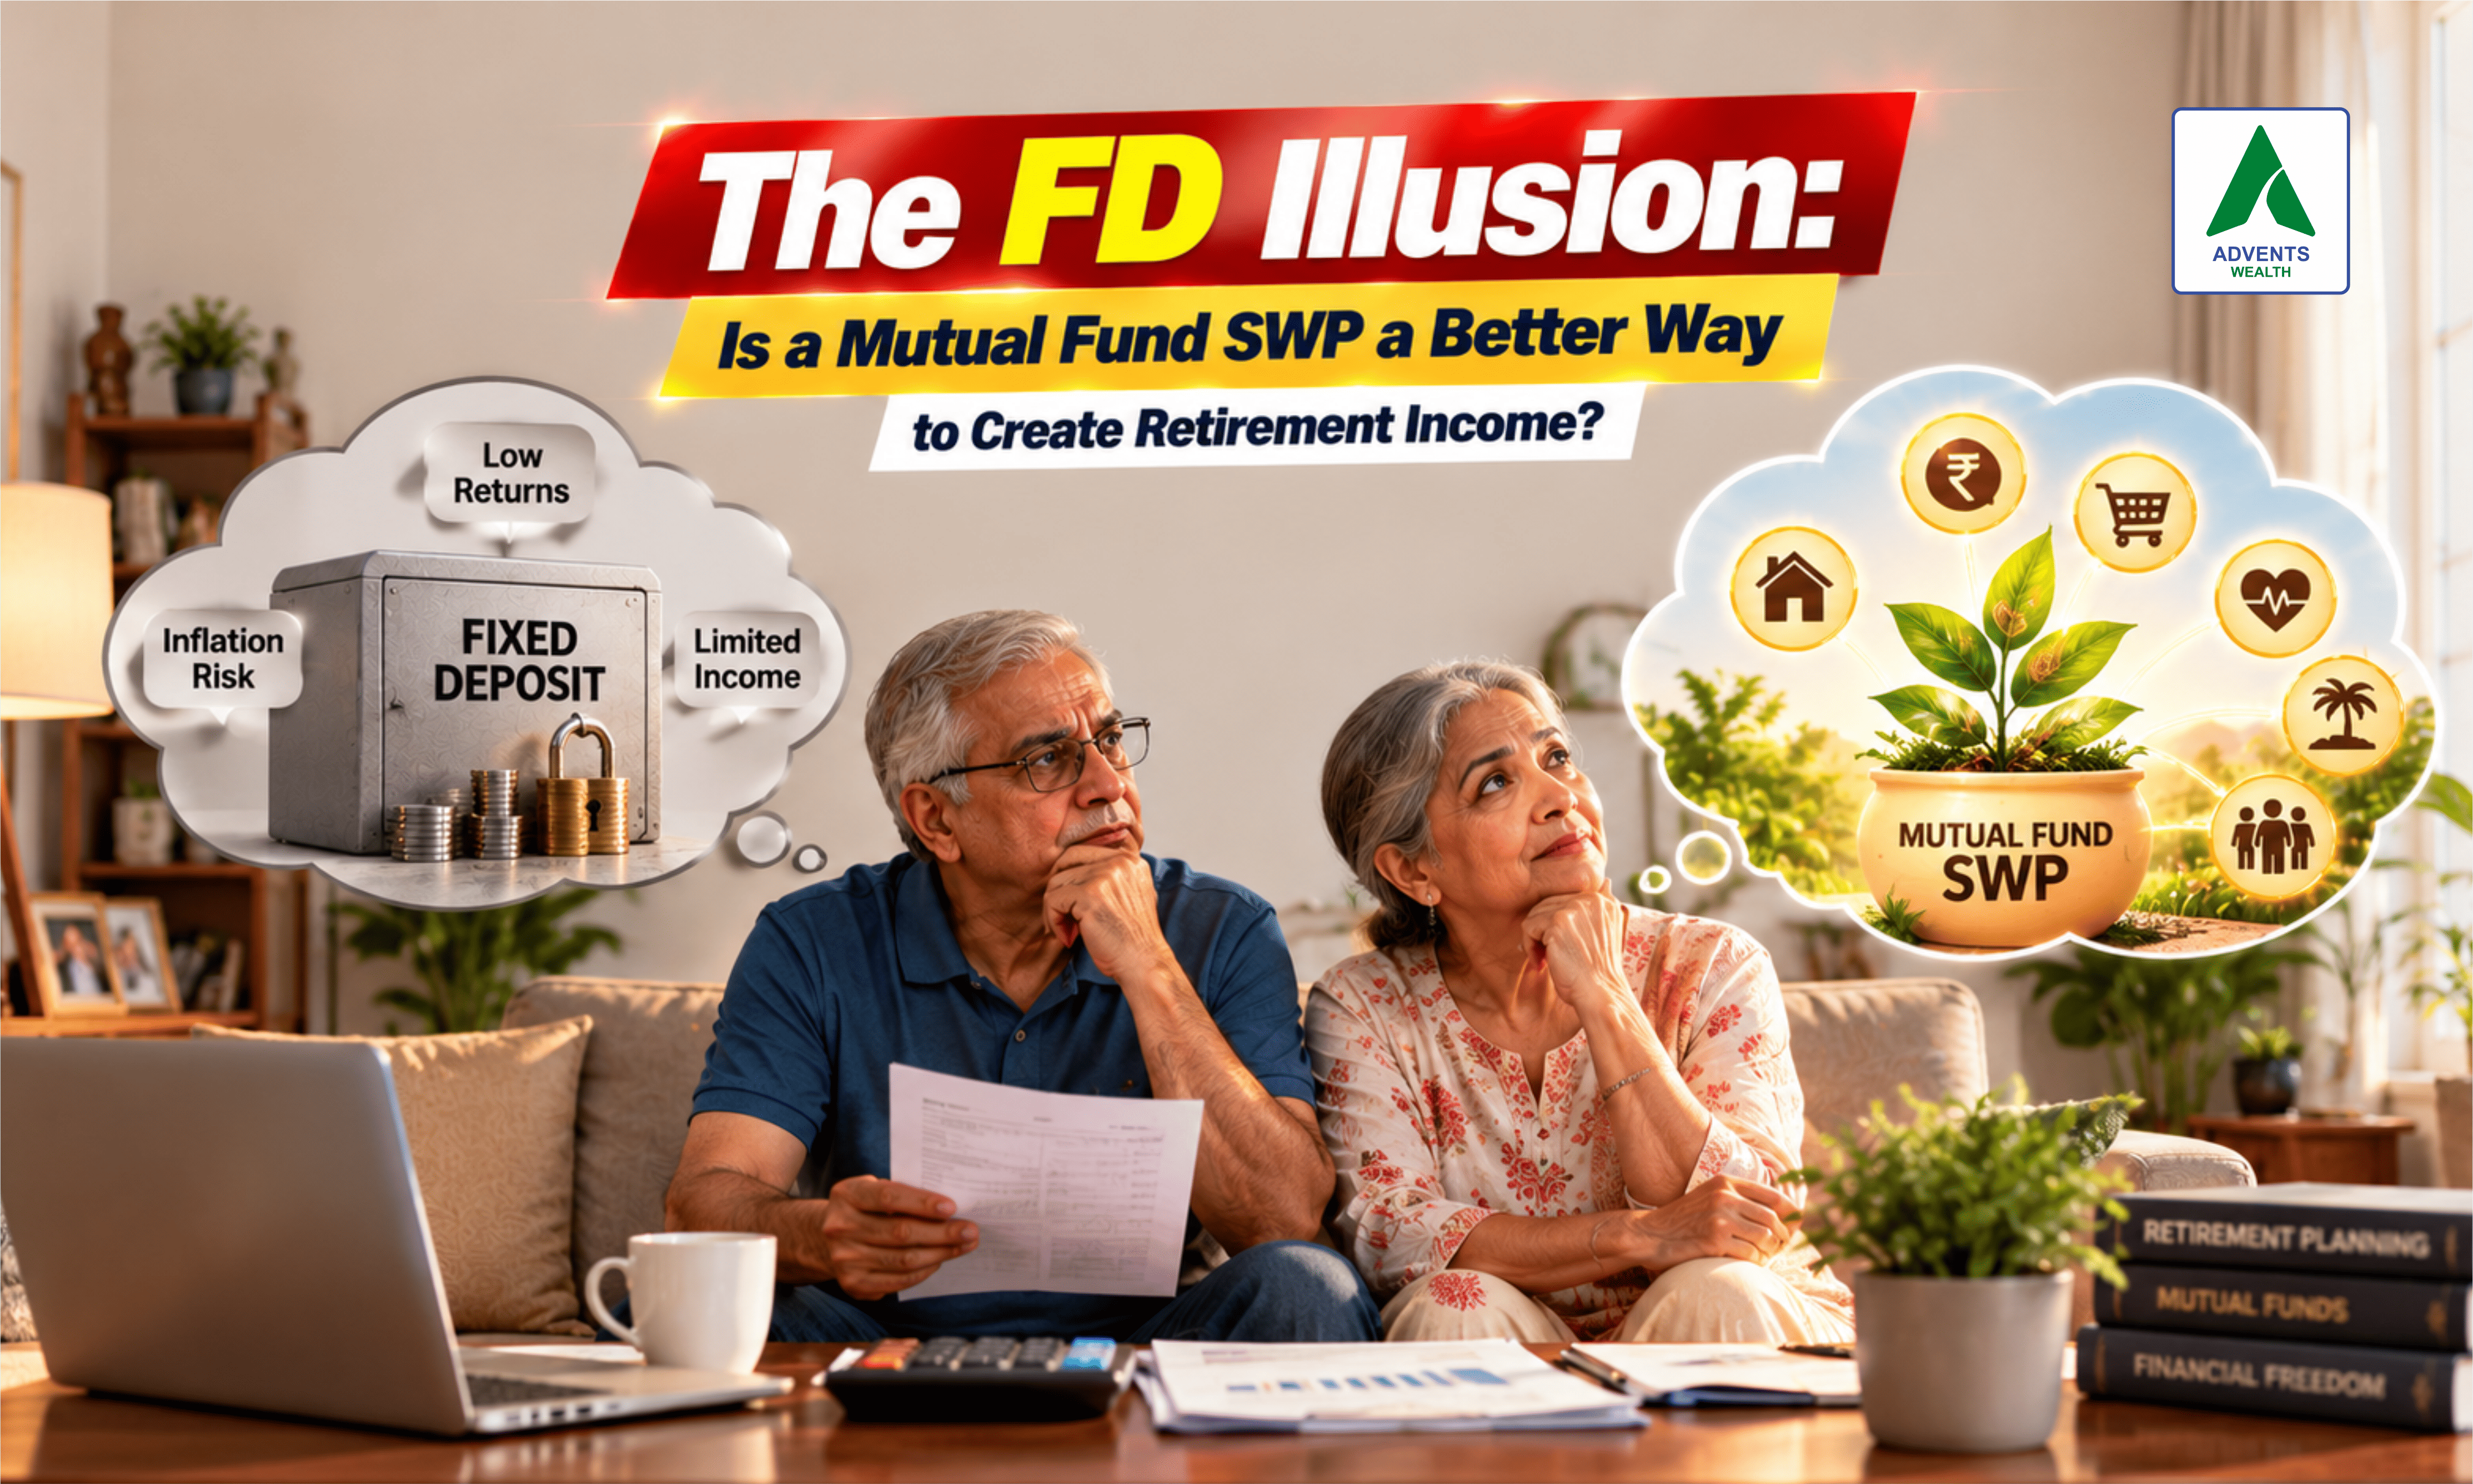
For many Indian households, fixed deposits (FDs) have traditionally been the preferred option. They offer predictable interest and a familiar way to manage savings. But when retirement can last 20–30 years, is depending entirely on FD interest enough?
A Systematic Withdrawal Plan (SWP) from mutual funds is another option worth understanding. The right choice depends on your income requirements, risk tolerance, tax position and financial goals.
The Hidden Challenge of Fixed Deposit Income
Imagine you invest ₹1 crore in a fixed deposit earning 7% annually. You receive ₹7 lakh in gross interest over a year, or approximately ₹58,333 per month before tax.
If you fall in the 30% tax bracket, the interest could leave you with approximately ₹4.9 lakh annually after tax, excluding cess and surcharge.
Now consider inflation. Your monthly expenses may increase because of healthcare, household costs, travel and lifestyle needs. The same ₹58,333 may not support the same lifestyle ten years later.
This does not make fixed deposits unsuitable. They can be useful for emergency reserves, short-term expenses and capital stability. The challenge is relying only on fixed deposits to fund a long retirement.
What Is a Systematic Withdrawal Plan (SWP)?
A Systematic Withdrawal Plan allows you to withdraw a fixed amount from your mutual fund investment at regular intervals, such as monthly or quarterly.
For example, if you invest a lump sum in a mutual fund and set up a monthly SWP of ₹30,000, the fund redeems the required units to make those payments.
Unlike FD interest, an SWP payment is not entirely profit. It can include your invested capital and capital gains.
Tax is generally calculated on the capital gains portion of the units redeemed, depending on the mutual fund category, holding period and applicable tax rules. This makes SWP taxation different from FD interest taxation, but it does not automatically make an SWP more tax-efficient.
Most importantly, an SWP is not guaranteed income. Market-linked investments can fall in value, and withdrawals during a market downturn can accelerate the depletion of your corpus.
FD vs SWP: Which Is More Suitable for Retirement?
| Factor | Fixed Deposit | Mutual Fund SWP |
|---|---|---|
| Income | Interest as per deposit terms | Regular redemption of units |
| Risk | Depends on institution and deposit terms | Market-linked |
| Taxation | Interest generally taxable at applicable slab | Capital gains taxation on redeemed units |
| Capital | Nominal value can remain intact if interest alone is spent | Can increase or decrease |
| Inflation | May struggle to keep pace | Potential for growth, but not guaranteed |
There is no universal winner. An FD may suit investors who prioritise predictable returns, while an SWP may suit those who can accept market risk in pursuit of long-term growth and flexible withdrawals.
How to Plan Monthly Retirement Income Through an SWP
Before using an SWP Calculator, understand your actual retirement expenses.
Start by separating essential expenses from discretionary spending. Keep an appropriate emergency reserve in accessible, lower-risk instruments rather than depending entirely on equity-oriented investments.
Next, assess your investment horizon, risk tolerance and existing assets. A combination of fixed deposits and suitable mutual fund investments may help balance liquidity, stability and growth.
Finally, choose a sustainable withdrawal amount and review it periodically. There is no fixed withdrawal percentage that guarantees your money will last throughout retirement. Consider market performance, inflation, taxation and your changing expenses.
Build a Retirement Income Strategy Around Your Life
At Advents Wealth, retirement planning is approached through individual financial goals, cash-flow requirements and risk assessment.
If you are looking for a financial planner in Thane, a structured review can help you understand how your FDs, mutual funds and other investments can work together to support your retirement.
The objective is not to replace every FD with an SWP. It is to create a retirement income strategy that balances today's needs with tomorrow's financial security.
Disclaimer: Mutual fund investments are subject to market risks. SWP withdrawals and returns are not guaranteed and may reduce your invested capital. FD interest and mutual fund capital gains are subject to applicable taxation. This article is for educational purposes only and is not personalised investment or tax advice.
Have questions on this topic?
Our wealth advisors can guide you based on your exact financial situation.