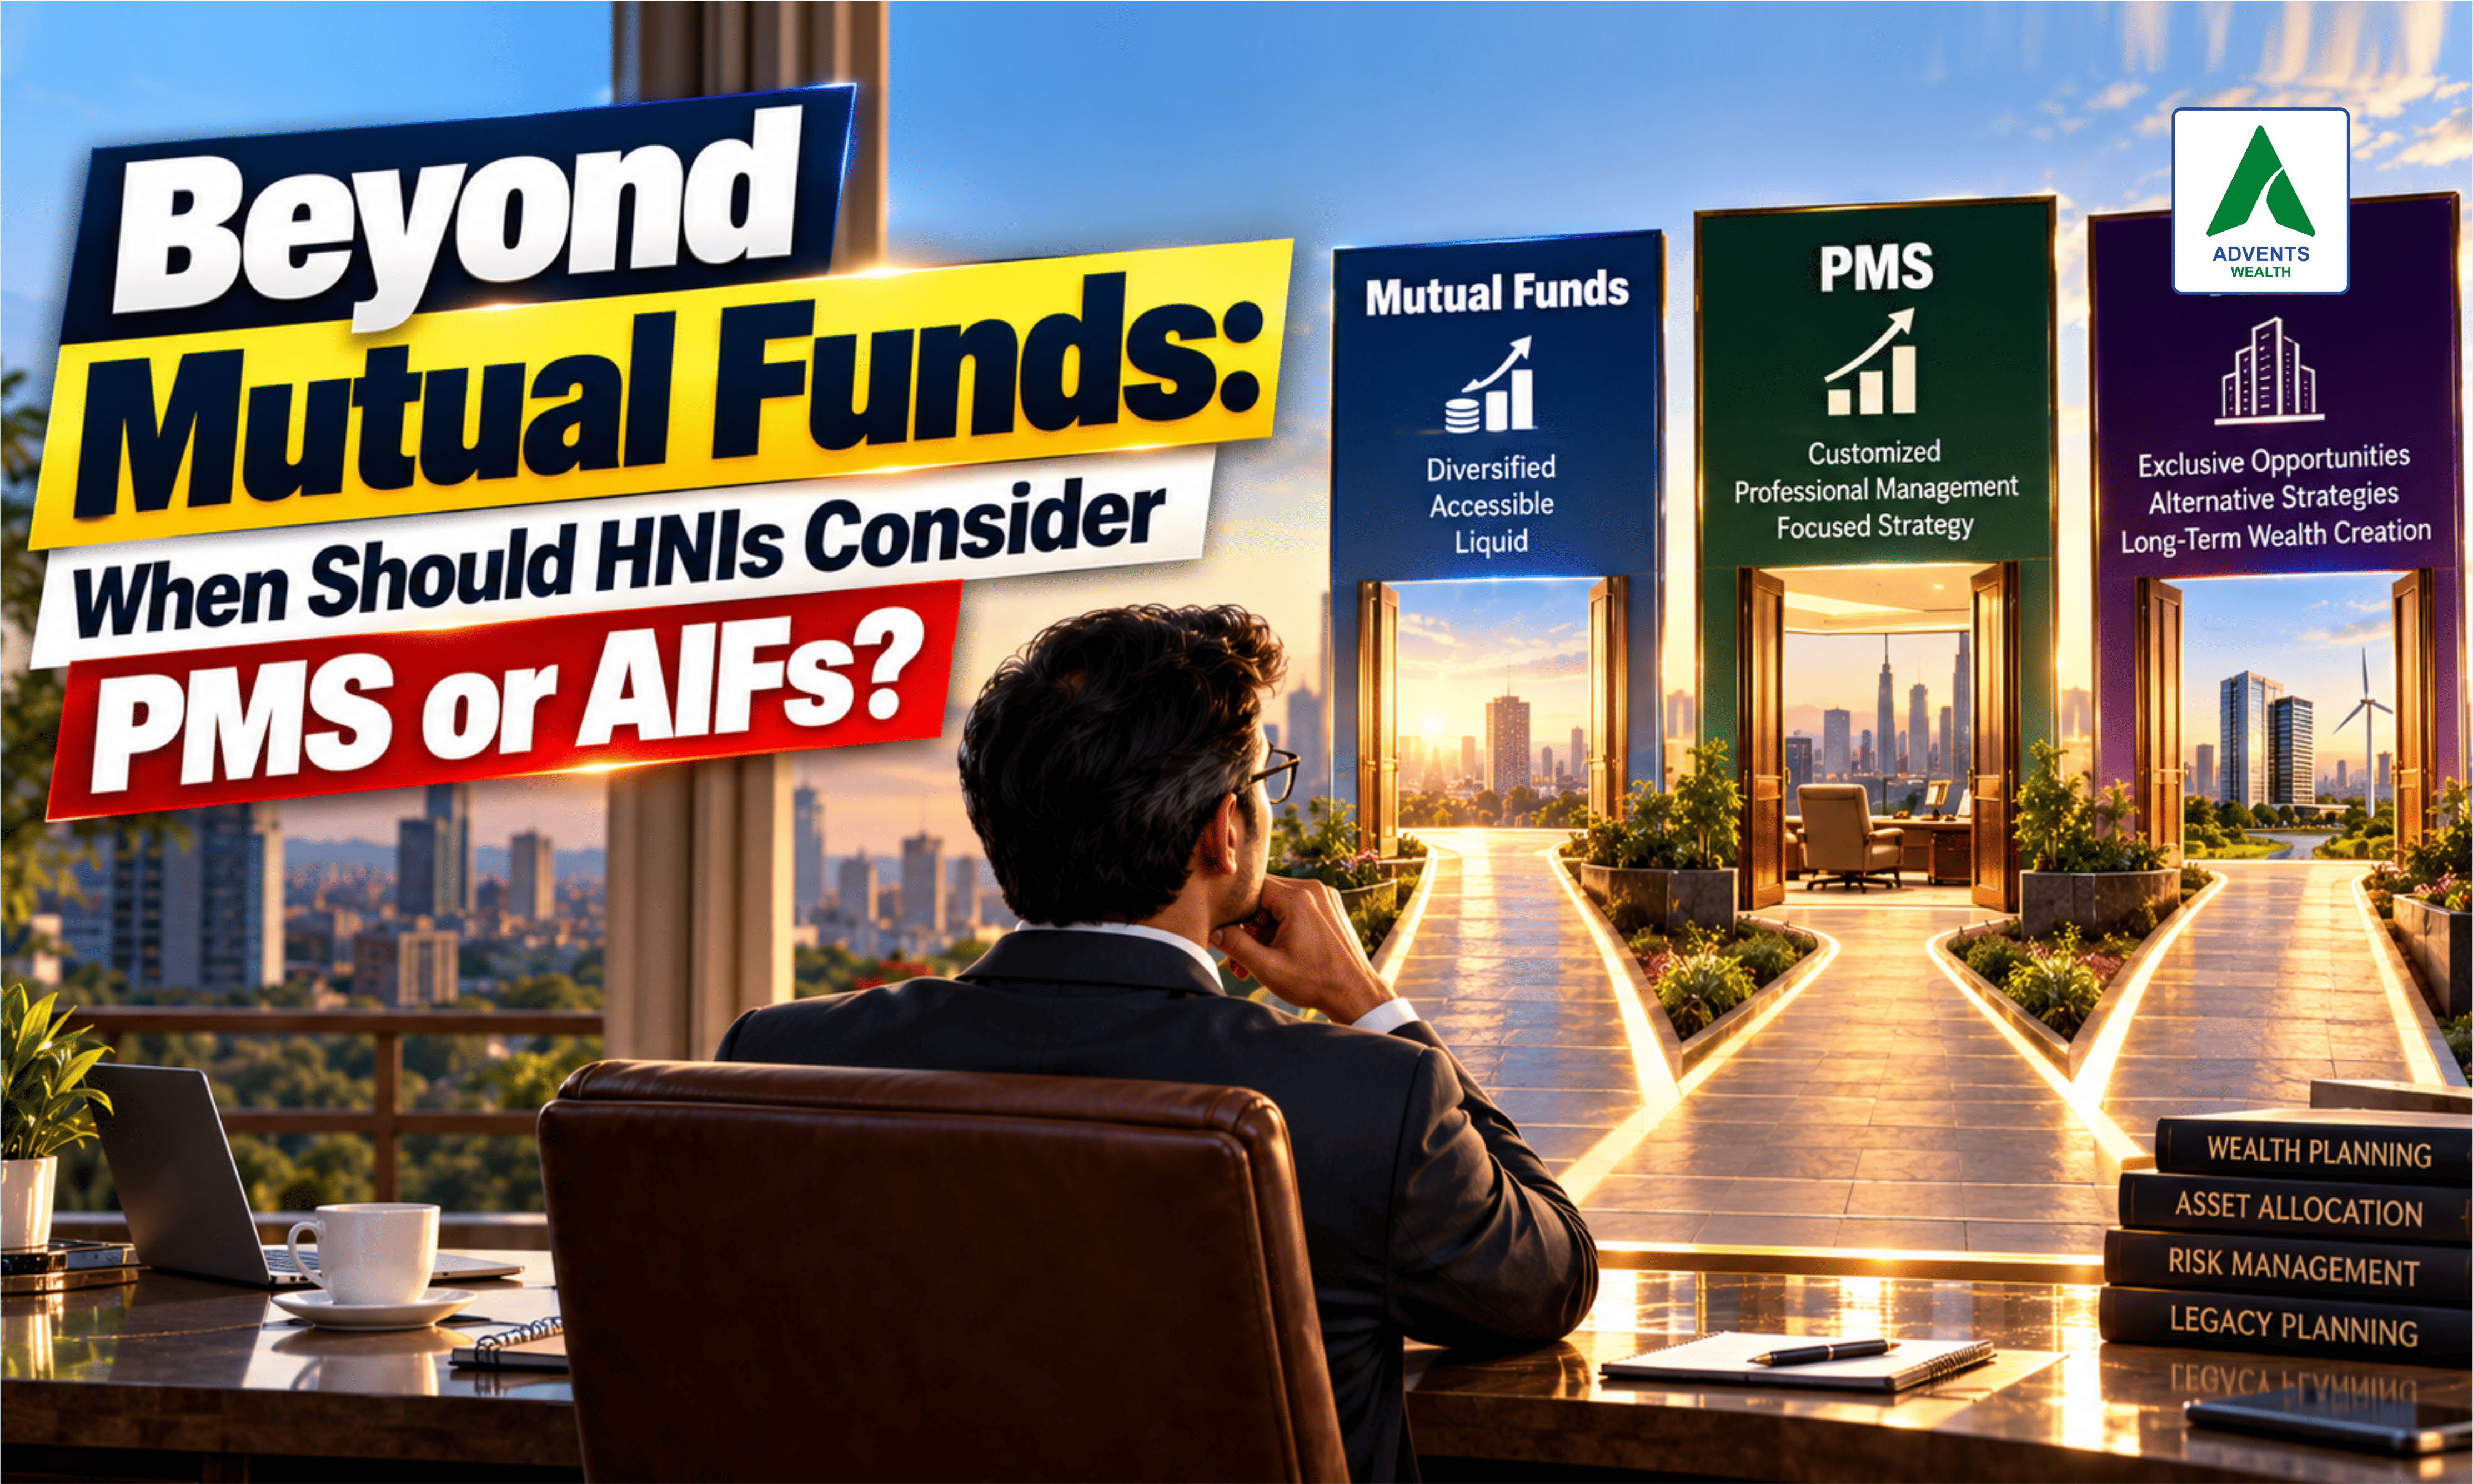
As wealth grows, investment decisions often become more complex. A business owner may want greater control over their investment portfolio. A senior professional may be looking for specialised investment strategies. An HNI may want to explore opportunities beyond traditional mutual funds.
This is where Portfolio Management Services (PMS) and Alternative Investment Funds (AIFs) enter the conversation.
But are PMS and AIF better than mutual funds? Not necessarily. Each investment option serves a different purpose. Understanding their structure, risks and suitability is more important than choosing the most sophisticated product.
Why Do HNI Investors Consider PMS and AIF?
Mutual funds remain an effective investment option for investors across different income and wealth levels. They offer diversification and professional management through a pooled investment structure.
However, investors with larger portfolios may have more specific requirements, such as customised investment strategies, concentrated equity exposure or access to private-market investments.
For example, a business owner may want a portfolio that considers their existing business exposure. An experienced investor may be interested in a specialised equity strategy. Another HNI may want to explore private equity or private credit opportunities.
The important question is whether these requirements justify moving beyond a conventional mutual fund portfolio.
PMS vs AIF: Understanding the Key Differences
Although both are designed for investors seeking specialised strategies, their structures are different.
1. Portfolio Management Services (PMS)
PMS involves professional management of an individual investor's portfolio under an agreed investment mandate.
Unlike mutual funds, where investors hold units in a pooled scheme, PMS investors generally hold securities directly in their own demat accounts.
PMS can offer greater portfolio customisation, transparency of individual holdings and strategies designed around specific investment objectives.
In India, the generally applicable minimum investment requirement for PMS is ₹50 lakh, subject to regulatory provisions and applicable exceptions.
However, greater customisation does not mean lower risk. Concentrated portfolios can experience significant fluctuations and losses.
2. Alternative Investment Funds (AIFs)
An Alternative Investment Fund is a privately pooled investment vehicle that collects money from investors and invests according to a defined strategy.
Depending on its category, an AIF may invest in private equity, venture capital, private credit, listed securities or other permitted opportunities.
AIFs generally have a minimum investment requirement of ₹1 crore, subject to applicable regulatory exceptions.
Unlike PMS, where each investor has a separate portfolio, AIF investors typically participate through units or interests in a pooled fund.
Liquidity can be limited, particularly in strategies involving unlisted investments. Investors should understand the fund's tenure, exit conditions, valuation process, fees and potential losses before committing capital.
PMS vs Mutual Funds vs AIF: What Should You Compare?
| Factor | Mutual Funds | PMS | AIF |
|---|---|---|---|
| Structure | Pooled investment | Individual portfolio | Pooled investment |
| Customisation | Limited | Higher | Depends on fund strategy |
| General minimum | Scheme-specific | ₹50 lakh | ₹1 crore |
| Liquidity | Generally higher, scheme-dependent | Depends on holdings and terms | Often restricted |
| Suitable for | Broad investor base | Eligible investors seeking customised portfolios | Eligible investors seeking specialised strategies |
Three Questions to Ask Before Investing
Before considering PMS or AIF investment, evaluate three things:
1. Does your existing portfolio need something different? A larger corpus alone is not a reason to choose a specialised product. Identify the specific investment requirement.
2. Can you accept the risks and liquidity restrictions? Consider your investment horizon, financial commitments and ability to withstand losses.
3. Do you understand the strategy and costs? Review the investment philosophy, fees, tax implications, manager experience and downside risks. Never select a product based only on projected returns.
Make Your Wealth Strategy More Purposeful
PMS and AIFs are not automatic upgrades from mutual funds. They are different investment structures that may suit specific financial requirements.
At Advents Wealth, the focus is on evaluating investment opportunities around your goals, risk profile and overall portfolio. If you are looking for a financial planner in Thane, a structured portfolio review can help you understand whether mutual funds remain suitable or whether PMS and AIF strategies deserve consideration.
The objective is not to own more complicated investments. It is to build a portfolio that reflects your wealth, your priorities and the financial future you want.
Disclaimer: PMS and AIF investments involve market and product-specific risks. Minimum investment requirements, eligibility, liquidity, fees and taxation are subject to applicable regulations and product documents. This article is for educational purposes only and is not personalised investment advice.
Have questions on this topic?
Our wealth advisors can guide you based on your exact financial situation.