Choosing a mutual fund should be straightforward: understand its strategy, know where your money is invested and decide whether it fits your financial goals.
But when schemes have confusing names, similar portfolios or descriptions that are difficult to interpret, making informed investment decisions becomes harder.
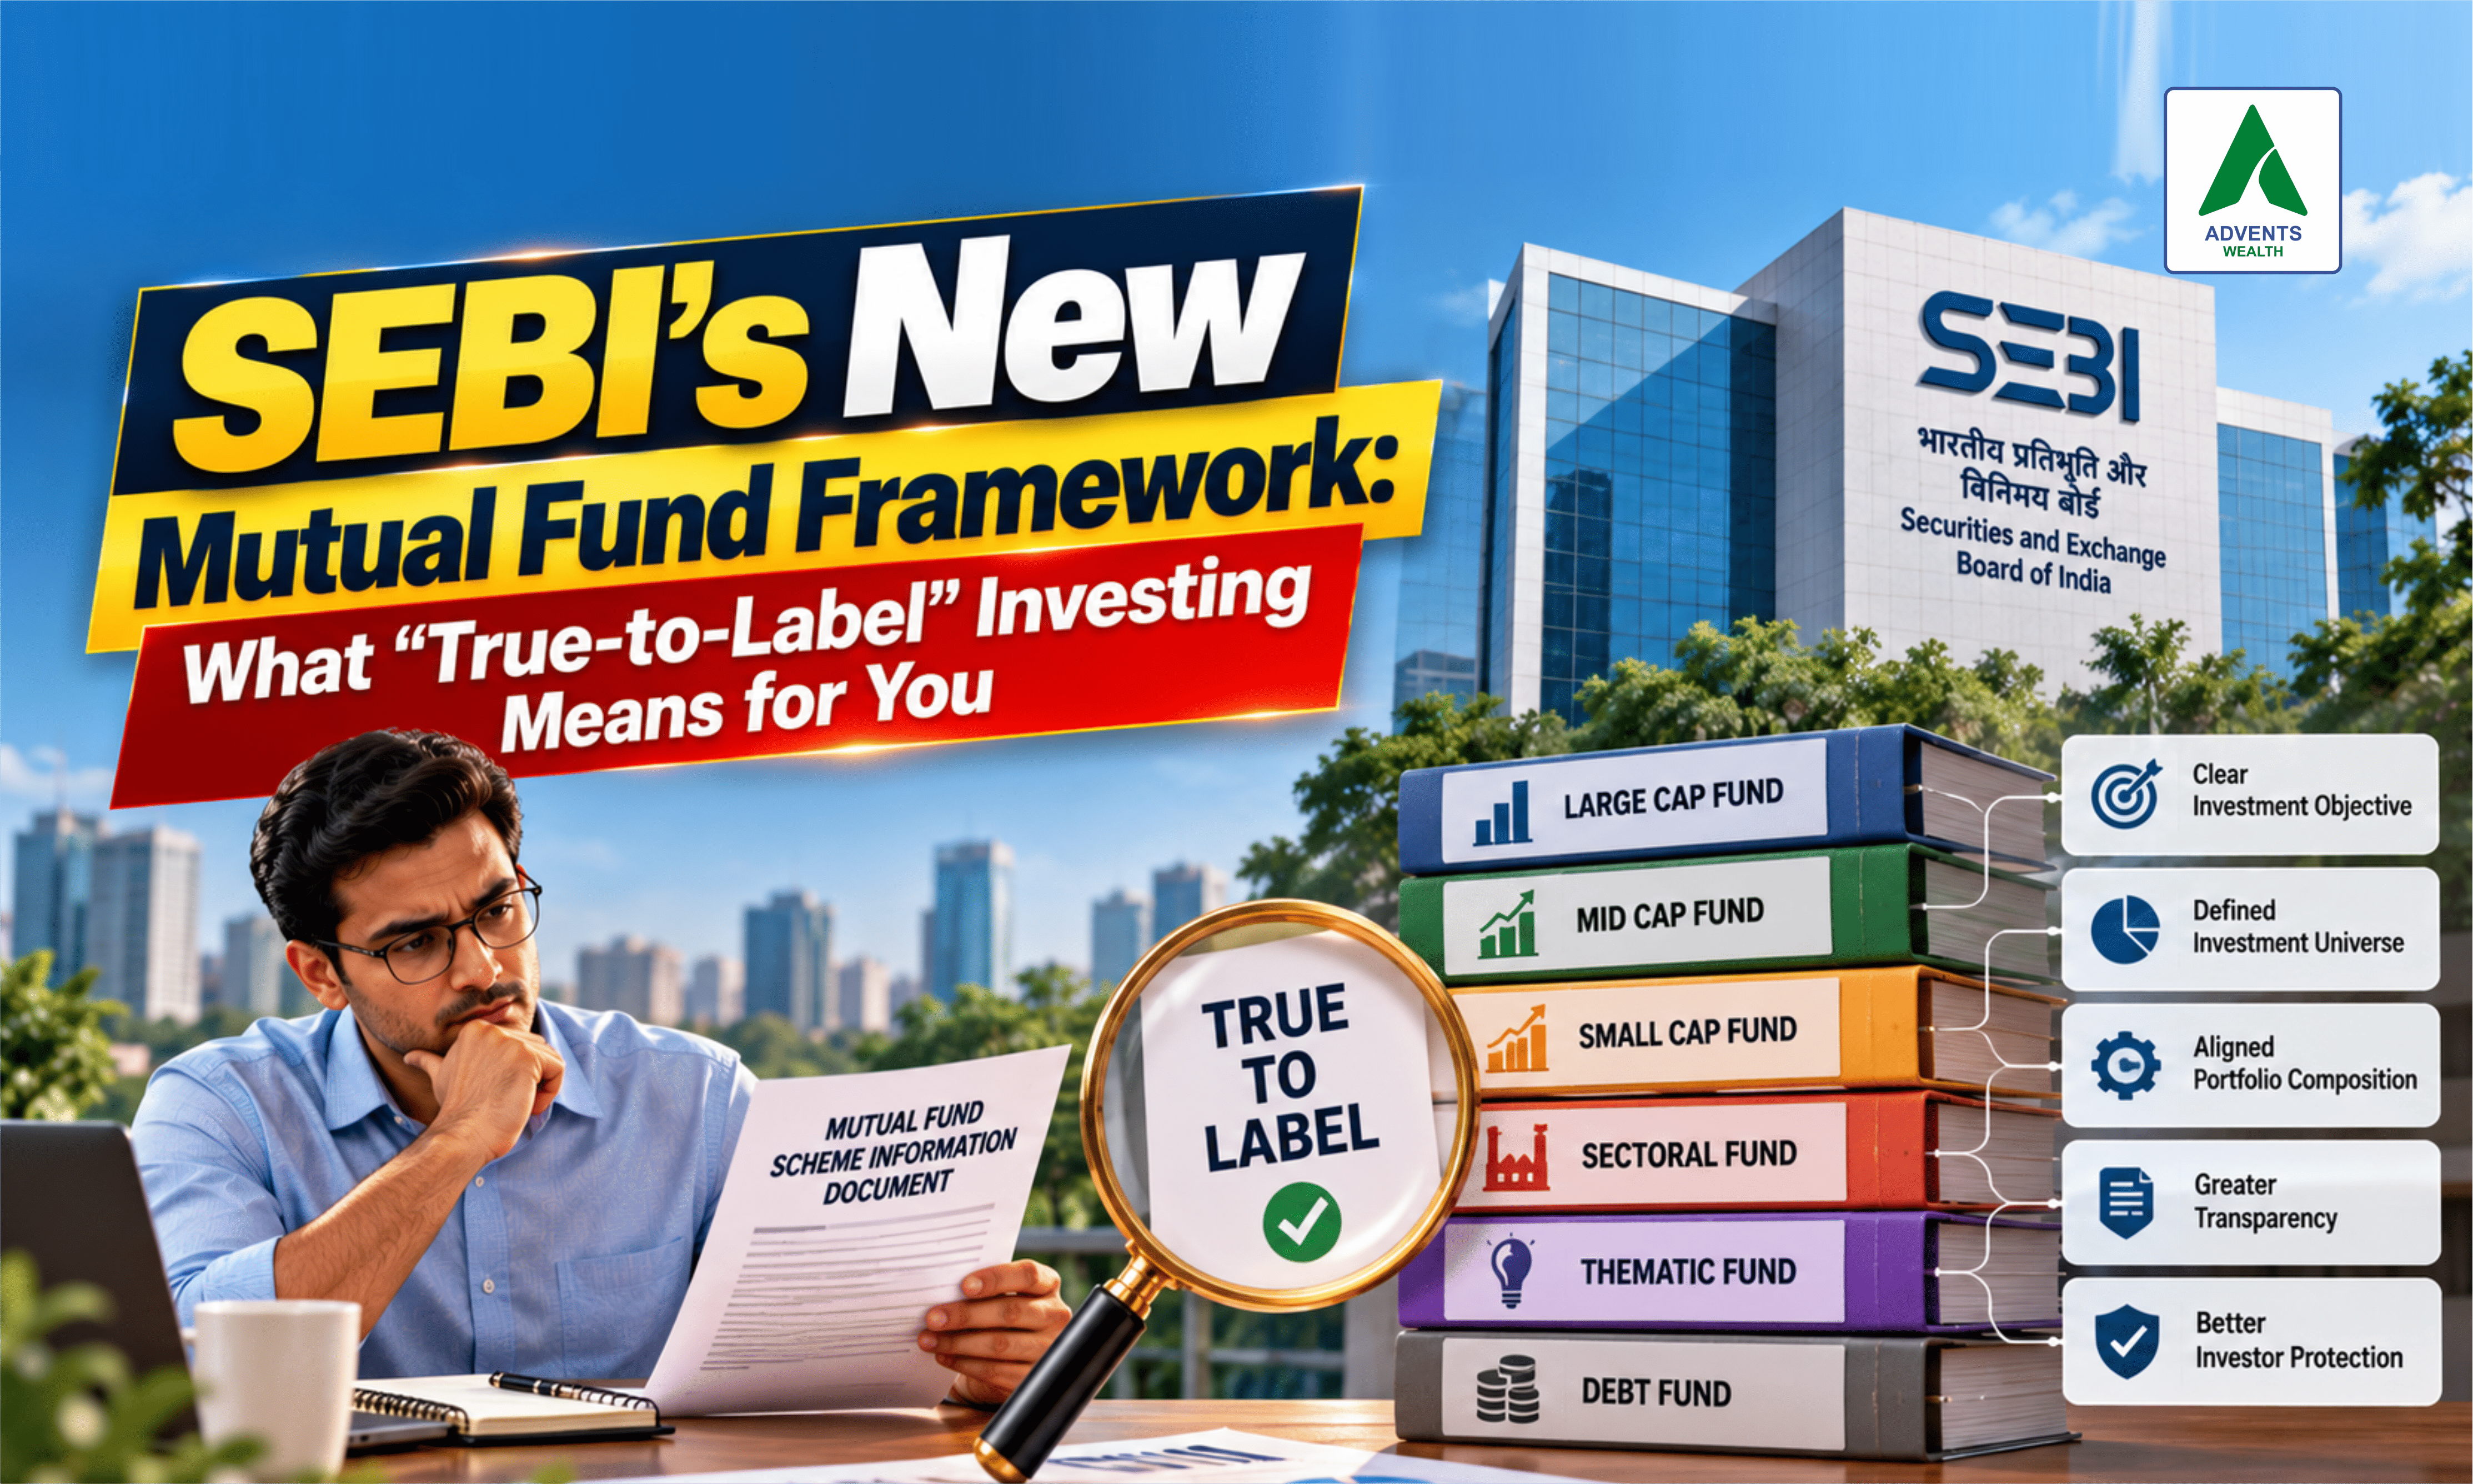
SEBI's revised mutual fund categorisation framework, introduced through its February 26, 2026 circular, aims to make scheme categories and descriptions more consistent. The SEBI (Mutual Funds) Regulations, 2026, which came into effect on April 1, 2026, provide the broader regulatory framework.
For investors, one important concept stands out: true-to-label investing. Here is what it means and why it deserves your attention.
1. True-to-Label: When a Fund's Name Must Match Its Strategy
A mutual fund's name should help investors understand what the scheme actually does.
Under the revised framework, scheme names must correspond to their prescribed SEBI categories. The description of the scheme in its offer documents and marketing material must also follow the applicable category description. Names that highlight only the return aspect of a scheme are not permitted.
Why does this matter?
Imagine choosing a fund because its name suggests an attractive investment opportunity, only to discover that its actual mandate is different from what you expected.
Standardised naming and descriptions can make comparisons easier and reduce confusion. However, a familiar or standardised category name does not guarantee that a scheme will perform well. Investors must still examine the investment objective, portfolio, benchmark, costs and risks.
2. Mutual Fund Portfolio Overlap Gets More Attention
Another important change concerns portfolio overlap.
SEBI has permitted mutual funds to offer both Value and Contra schemes, subject to a maximum 50% portfolio overlap between the two. Sectoral and thematic equity schemes must also meet prescribed overlap limits against other equity schemes, except large-cap schemes.
For existing sectoral and thematic schemes, the framework provides a three-year period to meet the applicable overlap requirements.
This matters because two schemes with different names may still provide similar underlying exposure.
For investors, the lesson is simple: do not judge diversification by the number of funds in your portfolio. Review their holdings, sector exposure and investment strategies to understand what each scheme contributes.
3. Life-Cycle Funds Bring a Goal-Based Approach
The revised framework recognises Life-Cycle Funds as a distinct mutual fund category.
These are open-ended funds with a predetermined maturity and a glide-path strategy. Their asset allocation can change as the target maturity approaches, with investments spread across permitted asset classes such as equity, debt, InvITs and gold and silver instruments.
For example, someone planning for a financial goal several years away may consider whether a fund with a suitable target maturity and allocation strategy fits their requirements.
However, Life-Cycle Funds are not identical. Their maturity dates, allocation ranges, investment strategies and costs can differ. Read the scheme documents carefully before investing.
4. Specialised Investment Funds Expand the Investment Landscape
Specialised Investment Funds (SIFs) are another development in India's investment landscape. They operate under a separate SEBI framework and offer more specialised investment strategies than conventional mutual fund schemes.
The general minimum investment threshold is ₹10 lakh across an investor's SIF strategies at the Permanent Account Number (PAN) level. Accredited investors are exempt from this requirement.
Depending on the strategy, SIFs may use specialised approaches, including permitted long-short investment strategies. This flexibility can also involve greater complexity and risk.
An SIF is not automatically better than a conventional mutual fund. Investors should understand its strategy, liquidity, costs, potential losses and suitability before considering it.
What Should Mutual Fund Investors Do Now?
Regulatory changes are a good reason to review your investments, but they do not automatically mean you need to switch schemes.
Start with three practical checks:
Review scheme mandates: Understand whether each fund's actual strategy matches your expectations.
Check portfolio overlap: Identify whether multiple schemes provide similar exposure.
Revisit your financial goals: Ensure your investments remain aligned with your time horizon, risk tolerance and asset allocation.
Before making changes, consider exit loads, capital gains tax and any applicable scheme-specific conditions.
At Advents Wealth, investment decisions begin with the investor's goals rather than the latest product trend. If you are looking for a financial planner in Thane, a structured portfolio review can help you understand how your investments work together and whether any adjustments are appropriate.
The real benefit of regulatory reform is better-informed decision-making—not more frequent portfolio changes.
Disclaimer: This article is for educational purposes only and does not constitute personalised investment advice. Mutual fund and SIF investments are subject to market risks. Regulatory requirements and scheme-specific conditions may change. Refer to the latest SEBI regulations, circulars and scheme documents before making investment decisions.
Have questions on this topic?
Our wealth advisors can guide you based on your exact financial situation.